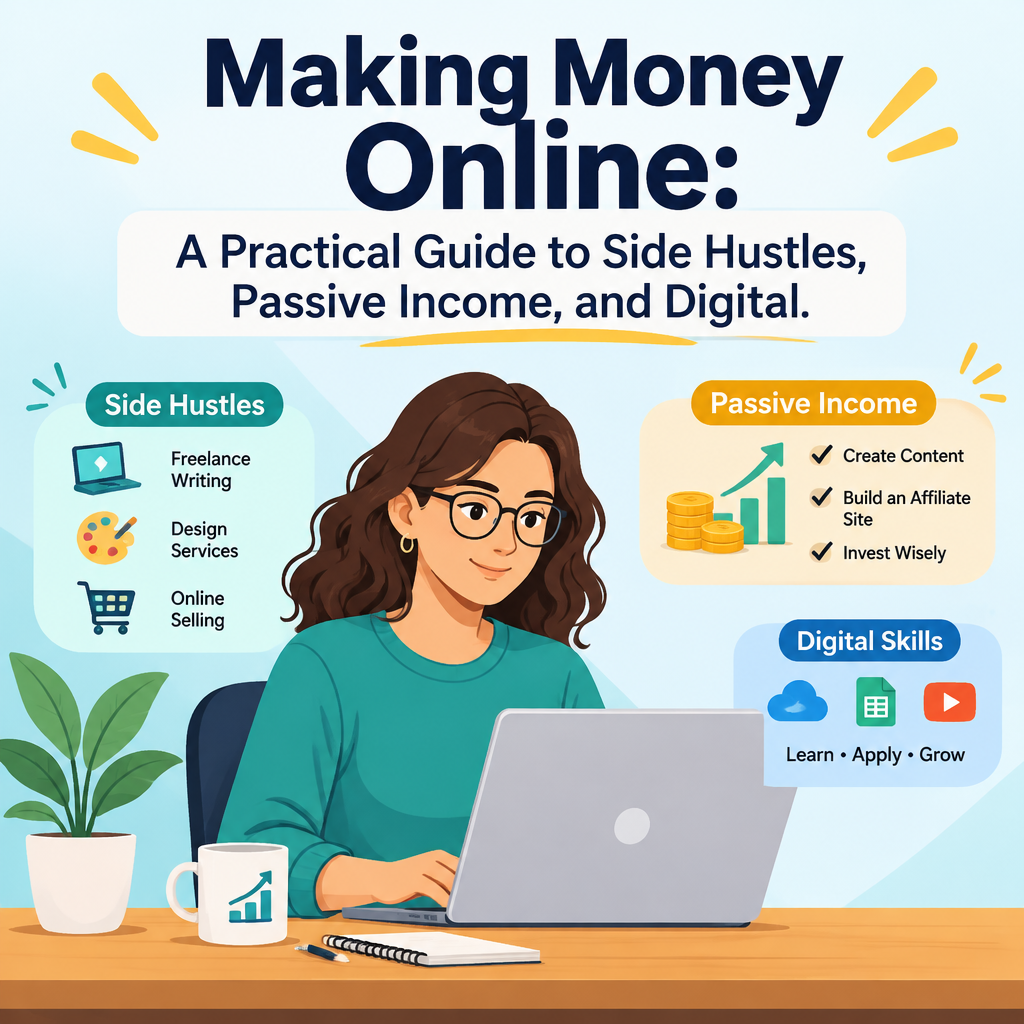
Making Money Online: A Practical Guide to Side Hustles, Passive Income, and Digital Business
Making money online means earning revenue through digital work, products, services, or assets, using the internet to find customers, deliver value, and collect payment. The practical versions are freelance services, remote work, online businesses, and carefully built passive-income assets—not mysterious systems that pay while you sleep.
Online income can help pay bills, build savings, or grow into a full-time business, but the right route depends on your skills, time, risk tolerance, and need for cash. Some models trade hours for money; others require months of product development, audience-building, or testing before revenue appears. That difference matters when rent is due next week.
The Penny Hoarder’s 2026 State of Savings in America Survey found that 44% of Americans do not have $1,000 in emergency savings and only 35% have a dedicated emergency fund. Those figures are a useful reminder: revenue is not the same as financial security. A side hustle works better when you set aside money for taxes, slow periods, and surprise expenses instead of counting every sale as spendable income.
Frankly, most claims about easy online money leave out the labor, fees, competition, and risk. Here’s the practical version: choose one business model, test whether customers will pay, and expand only when the numbers support it.
What Is Making Money Online?
Making money online is earning from work or assets delivered, sold, or managed through internet-based channels. The phrase covers several distinct business models, and treating them as one thing causes poor decisions. A remote employee earns wages through an online workplace; a freelancer sells a service; a digital shop sells products; an investor may earn returns from financial assets. Each has a different path to revenue and a different set of costs.
The simplest starting point is usually a service. A writer, bookkeeper, designer, tutor, programmer, or virtual assistant can sell a defined skill to a customer, then deliver the work remotely. You do not need a giant audience or a warehouse, though you do need a reliable offer, clear terms, and proof that you can do the job. Platforms can help customers find you, but they may charge fees and control parts of the customer relationship.
Digital products work differently. A course, template, stock image collection, paid newsletter, or software tool can be created once and sold repeatedly, which creates scalability if demand exists and delivery costs stay manageable. But “create once, sell forever” is sales copy, not a business plan. Products need updates, customer support, marketing, payment processing, and a reason for buyers to choose yours.
Passive income is revenue that can continue after the initial work, but it is rarely effortless or truly hands-off. A rental property needs maintenance; an affiliate site needs useful content and traffic; an investment carries market risk; a subscription product needs retention and technical upkeep. Automation can reduce repeated tasks, yet it cannot fix a weak offer or manufacture demand.
When I compare these models, the useful questions are concrete: Who pays? What do they receive? How much does it cost to acquire and serve them? What is the expected ROI after fees, taxes, and time? The Small Business Administration recommends researching customers and competitors before investing heavily; its guide to market research and competitive analysis is a sensible starting point. A business becomes credible when customers receive real value, not when its sales page uses louder promises.
Core Benefits and Importance
Online income can add flexibility and another source of revenue, but those benefits depend on the model and the person running it. It is not a guaranteed shortcut out of financial pressure. The useful advantages are practical, and so are the trade-offs.
- Lower-cost testing: Many service businesses can begin with an existing computer, a basic portfolio, and a clear offer. You can contact a small group of likely customers before paying for software, branding, or advertising. That does not make the work free; your time has value, and platform fees can trim each payment.
- More control over the offer: A freelancer can choose a specialty, set a price, and refine the service based on customer feedback. A business owner can decide which products to keep and which channels to use. Control comes with responsibility, though—there is no manager to fix missed deadlines or chase invoices for you.
- Multiple revenue streams: A person might combine a part-time remote role with freelance work, then add a digital product after learning what customers repeatedly need. Several streams can reduce dependence on one client or employer, but spreading attention across five untested ideas usually creates five weak efforts. Build one dependable source before adding another.
- Potential to scale: A service can become more efficient through repeatable processes, packaged offers, or a small team; a product can reach additional buyers without repeating every production task. Scale is not automatically profit. More customers can also mean more support, refunds, hosting costs, or advertising expense.
- A path toward stronger savings: Extra income can help cover irregular bills, pay down costly debt, or build an emergency reserve. The Penny Hoarder’s 2026 savings survey reported that 44% of Americans lack $1,000 in emergency savings, while 35% keep a dedicated emergency fund. The numbers do not prove that online work solves the problem, but they underline why a cash buffer matters when income fluctuates.
Here’s the kicker: a second income stream can make finances less fragile only if you manage it carefully. Set aside a portion of each payment for taxes and operating costs, then decide what can go toward savings or household spending. That is stewardship, not stinginess; work should support a person’s well-being and obligations, rather than feeding a platform’s appetite for unpaid labor.
Step-by-Step Guide to Building Online Income
Start small. A sensible plan moves from a customer problem to a tested offer, then to repeatable delivery and measured growth. I would rather see a simple service earn its first legitimate payment than a polished website spend six months waiting for traffic.
- Set a financial target and a time limit. Decide what the income needs to do: bring in $300 a month, replace a specific bill, or test a full-time business idea. Separate the target from wishful projections. Write down how many hours you can give the work, what savings you can risk, and the date you will review the results. If you need cash this month, prioritize paid services or short-term contract work over a product that may take months to sell.
- Take stock of skills, tools, and constraints. List skills people already pay for, not just interests you enjoy. Consider your work history, credentials, equipment, schedule, and local rules. A strong offer might be bookkeeping for independent tradespeople, editing for researchers, tutoring in a subject you know well, or basic website maintenance for local firms. Keep the starting costs low. If a model requires debt, expensive coaching, or a large inventory order before you have customers, examine the risk closely.
- Choose a customer and verify demand. “Anyone who needs help” is not a useful market. Identify a specific group, learn what problem keeps costing them time or money, and speak with potential buyers. Review competing services, prices, and customer complaints. The SBA’s market research guide explains how to assess demand, market size, and competition. Do not confuse social-media likes with buying intent; ask what people currently pay to solve the problem.
- Create one clear offer and ask for a sale. State the result, scope, timing, price, and what the customer must provide. A narrow offer is easier to explain and deliver than a vague promise to “grow your business.” For a product, make a small version, sample, or preorder test before building a large catalog. For services, contact likely customers directly or use a reputable marketplace while checking its fees and rules. No sale is useful information; it may point to a price, audience, or offer that needs revision.
- Deliver well and track the real economics. Agree on deadlines and payment terms in writing. Record revenue, refunds, platform charges, software, supplies, advertising, and hours worked. A $500 project can look attractive until it consumes 30 hours and requires costly revisions. Track customer acquisition cost, repeat purchases, effective hourly earnings, and ROI. Keep personal and business transactions organized, even if the business is small; messy records make tax time and pricing decisions harder.
- Protect income, taxes, and savings. Online earnings may be taxable even when a platform does not issue a particular form. The IRS explains reporting and recordkeeping for gig work in its Gig Economy Tax Center; check the rules that apply to your circumstances and location. Keep money for tax obligations separate from spending cash. Build an emergency fund gradually, starting with a modest target you can reach, then increase it as income becomes more reliable. A buffer helps prevent one broken laptop or slow month from forcing expensive borrowing.
- Automate only stable, repeatable tasks. Once a service or product sells consistently, automate scheduling, invoices, email receipts, or delivery where it improves accuracy. Review every automation for errors and customer experience. Automation should remove repetitive admin, not turn customer support into a maze. Reinvest only after you know what is working, and test one change at a time so you can see whether it improves sales or reduces costs.
The sequence matters. Find demand, prove the offer, deliver value, then improve the system. A business does not become passive because you bought a scheduling app; it becomes more efficient when the work and customer response justify the tool.
Online Income vs. Traditional Employment
The biggest competitor to online business income is often a regular job. The two can also work together: employment may cover steady bills while a small online service tests whether self-employment suits you. Neither route wins in every situation. Compare predictability, control, costs, and benefits before assuming that a business is automatically better.
| Factor | Online income or side business | Traditional employment |
|---|
| Income pattern | Can vary by customer demand, project timing, platform rules, and sales | Often follows a regular pay schedule, though hours and job security can still change |
| Control | More choice over offers, customers, and schedule, depending on the model | Employer usually sets role, schedule, and many work processes |
| Startup costs | May include tools, fees, insurance, marketing, and unpaid setup time | Usually lower direct business costs, though commuting and work-related expenses may apply |
| Benefits and protections | Often must be arranged or funded by the worker | May include benefits, paid leave, or other protections, depending on employer and location |
| Growth | Can expand through higher prices, repeatable systems, products, or additional workers | Often tied to promotions, raises, or changing roles |
| Savings buffer | A reserve can help cover slow months and surprise expenses | A reserve still matters; stable pay does not eliminate emergencies |
There is no reliable universal figure for what an online business will earn, because results vary by industry, hours, price, skill, and customer demand. The Penny Hoarder’s 2026 State of Savings in America Survey found 44% of Americans have less than $1,000 in emergency savings, and only 35% have a dedicated emergency fund. Those are savings figures, not proof of business success, but they make one point plain: predictable cash reserves matter whichever work arrangement you choose.
When I compare the economics, I look past gross revenue. A worker with a steady paycheck may value paid leave and benefits; a freelancer may value flexibility but need to budget for unpaid admin time, taxes, and gaps between projects. For some households, the least risky move is to keep a job while testing a side hustle. That lets evidence—not a viral success story—decide whether to expand.
Common Mistakes to Avoid
A lot of online-business advice sells certainty where none exists. Be wary of anyone promising income without clear work, costs, and risk. The basic mistakes are not glamorous, but they are expensive.
- Buying tools before finding customers: A paid website, premium app, logo package, and course can create the feeling of progress without a single sale. Start with the minimum tools needed to test your offer. Upgrade after a real bottleneck appears, not because a sales page says professionals need it.
- Calling every repeatable revenue stream passive: Products, affiliate links, subscriptions, and investments all require some combination of setup, maintenance, capital, or risk. A video course may keep selling, but outdated lessons and unanswered customer questions can damage trust. Describe the ongoing work honestly so you can plan for it.
- Chasing several side hustles at once: Switching between dropshipping, short-form video, tutoring, and print-on-demand makes it difficult to learn what customers actually want. Pick one model for a defined test period. Review results against a few measures, such as paid orders, profit after costs, and hours required.
- Ignoring fees, taxes, and cash flow: Sales are not profit. Payment processors, marketplaces, returns, shipping, subscriptions, advertising, and taxes can reduce what remains. Keep records from the first transaction. The IRS guidance for gig workers is a useful reference, but tax treatment depends on individual facts and current rules.
- Trusting guaranteed-income pitches: Claims of effortless returns, pressure to pay immediately, and income that depends mainly on recruiting other sellers deserve extra scrutiny. The Federal Trade Commission offers guidance on multi-level marketing and related business claims. Read the compensation terms, identify real customer demand, and walk away from claims that cannot be checked.
- Neglecting savings because revenue is rising: A busy month does not guarantee a busy quarter. If all new income goes toward lifestyle upgrades, a slow season can become a debt problem. Create a routine for taxes, operating expenses, savings, and personal pay. The CFPB’s guide to building an emergency fund offers practical ways to start with small, regular contributions.
Let's be real: a side hustle is not a moral test, and a person with limited time or money does not need another lecture about discipline. Start with a model that fits your circumstances. Fair pricing, honest claims, and dependable service are better foundations than squeezing customers or workers to make a weak business look profitable.
Frequently Asked Questions
Can I make money online with no money?
Sometimes, but “no money” usually means using tools and skills you already have, while contributing substantial time. Freelance writing, tutoring, editing, or virtual assistance may need little cash to test, though you may still face platform fees, internet costs, or unpaid work while finding clients. Avoid paying for an expensive course or inventory before checking whether customers will buy. If a supposed free method asks for bank details, a large upfront payment, or recruitment of friends, stop and investigate.
How long does it take to earn money online?
There is no fixed timeline. A service provider with a marketable skill and customer contacts might find paid work sooner than someone building an audience or developing a software product, but no method guarantees a first sale by a certain date. Set a test period, track outreach and customer responses, then revise the offer if there is no traction. Do not treat a few sales as proof of dependable monthly income; repeat purchases and positive margins matter more.
What counts as passive income?
Passive income generally refers to revenue that continues with less day-to-day labor after setup, such as some investment returns, royalties, or sales of a maintained digital product. The label can be misleading: investments can lose value, products need support, and content needs updates and distribution. Ask what work remains, what capital is at risk, and how income may change. If a seller promises guaranteed returns without meaningful effort or risk, treat the claim skeptically.
Do I have to report income from online work?
Online income may have tax-reporting obligations even when a payment platform does not send you a tax form. Rules depend on where you live, the type of income, your business structure, and other details. Keep records of income and eligible expenses, and use the IRS Gig Economy Tax Center as a starting reference for U.S. gig work. For advice about your situation, consult a qualified tax professional or the appropriate tax authority in your country.
Final Thought
Online income is most useful when it solves a real customer problem and makes your own finances sturdier. It does not need to become a personal brand empire. A few reliable clients, a modest digital product, or a part-time remote role may be a better fit than a business that consumes every evening and still loses money.
Start with a service or product you can explain plainly. Check demand before making large commitments, write down your costs, and give the first test a clear finish line. If customers pay and the work produces a reasonable return for your time, improve what is already working. If they do not, adjust the offer or stop; sunk costs are not a reason to keep feeding a poor plan.
Most importantly, treat revenue as a tool, not a score. Set aside money for taxes and operating needs, build an emergency fund in manageable steps, and be honest with customers about what you can deliver. The steady work of serving people well may sound less exciting than a promise of effortless wealth, but it is a sounder base for a side hustle—and for a household that needs its income to last.
FAQPage JSON-LD